Modern vehicles have quietly become one of the most software-dependent consumer products on the market. We used to look at engines mostly in terms of their size and hardware, but now what really matters is the software driving them—the software that enables a vehicle to brake, steer, sense its environment, download updates, and talk to its driver. This is not a minor transition; it has been profound, and it took place in a short time frame. It went from being an issue discussed only among engineers to becoming a requirement of modern vehicles. The manufacturers that used to compete primarily in horsepower, fuel efficiency, and passengers’ comfort are now competing in how many useful features their software solution can offer, as well as how well it works after production and how fast it is developed.
The current state of government safety records indicates how much this process has already advanced, and how fast it started to develop. The technology that has been on the market for less than a decade initially included just a few advanced features for auto drivers, but now is part of every new car sold in the USA, even though such a process does not happen as a result of a dramatic fall in the price for hardware, but due to the fact that the software programs that regulated this technology reached the necessary maturity to be implemented and tested among suppliers and users. The following chapters will explain how fast this process is going on, what drives this movement and what impact it will have on the development of the automotive industry.
The Scale of Software Adoption in Vehicles Today
According to the Partnership for Analytics Research in Traffic Safety (PARTS) — a joint initiative between nine major automakers and the U.S. Department of Transportation’s National Highway Traffic Safety Administration (NHTSA) — data drawn from roughly 98 million passenger vehicles sold in the United States, covering 168 models from model years 2015 to 2023, shows that by the 2023 model year, 10 out of 14 advanced driver assistance system (ADAS) features had surpassed 50% market penetration, with five features exceeding 90%. Just two years earlier, in the 2021 PARTS report, none of these features had crossed even the 75% mark. That shift — from zero features above 75% to five features above 90% within roughly two model years — is one of the clearest available signals that vehicle software has moved from optional add-on to default architecture across the industry.
This acceleration in software-defined features is precisely what’s driving investment further back in the pipeline — into the platforms that build, validate, and deploy that code in the first place.
Why Software Platforms Are Replacing Fragmented Vehicle Architecture
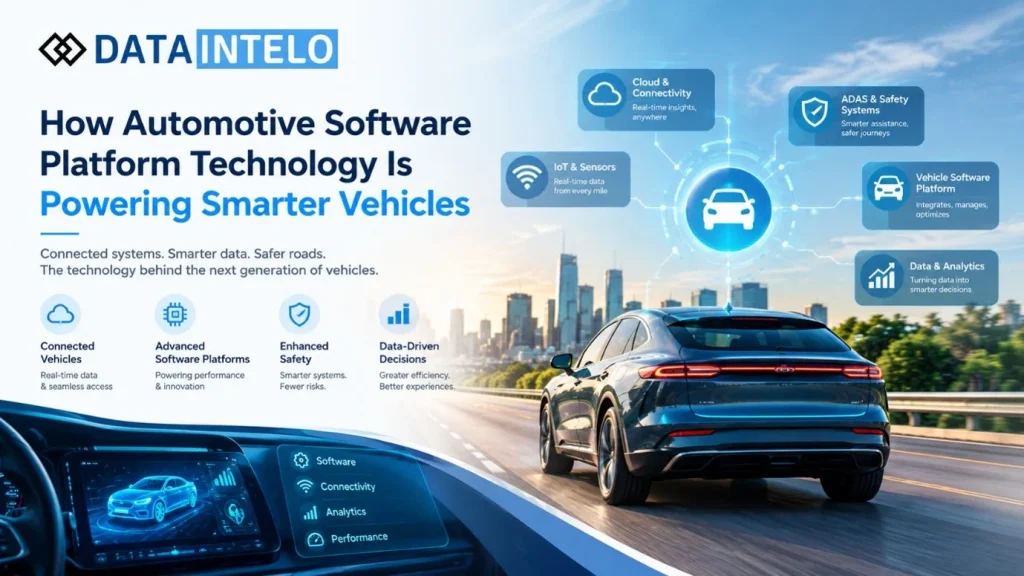
Vehicle electronics have historically relied on numerous separate electronic control units (ECUs), each handling an isolated function — windows, climate, infotainment, braking — with little shared infrastructure between them. That fragmented model is being replaced by centralized software platforms, for several concrete reasons:
- Centralized computing consolidates functions that once ran on separate isolated controllers into shared domain controllers, reducing integration complexity across vehicle programs.
- OTA updates enable manufacturers to deliver safety and feature updates remotely, without the requirement of going to a dealership. This is a common practice now when it comes to software-defined vehicle platforms.
- SDVs make it possible to separate features from hardware; thus, car manufacturers are able to change properties through software without having to make alterations to the hardware.
- Standardized middleware allows software components from different suppliers to run on a shared platform, cutting integration and validation time across vehicle programs.
Each of these shifts reduces the cost and time needed to bring new safety and convenience features to market — which is why the ADAS penetration jump documented by NHTSA’s PARTS program happened over just two model years rather than a full product generation.
Market Scale and Growth Trajectory
The investment behind this transition is measurable and accelerating. The Automotive Software Test Automation Market size was valued at USD 3.2 Billion in 2025 and is expected to reach USD 8.1 Billion by 2034, growing at a CAGR of 12.4% from 2026 to 2034, according to Dataintelo research. This increase in testing automation matters because as automobiles have become more software-defined, meaning more than 90% of the vehicle’s functions are controlled by software, it has become the most crucial engineering challenge to validate those codes without a corresponding increase in hours spent on manual tests, rather than a cost issue.
Software Platform Technology at a Glance
| Technology Layer | Function | Data Point |
| ADAS Feature Software | Collision warning, lane assist, automatic braking | 5 of 14 features exceed 90% penetration (NHTSA/PARTS, 2023 model year) |
| ADAS Feature Software (2021 baseline) | Same feature set, earlier report | 0 features exceeded 75% penetration (NHTSA/PARTS, 2021) |
| Software Test Automation | Validates vehicle code before deployment | Market growing at 12.4% CAGR, $3.2B (2025) to $8.1B (2034) |
| Software Developer Workforce | Builds and maintains platform code | 17.9% projected employment growth, 2023–2033 (BLS) |
This table illustrates a consistent pattern: every measurable layer of the automotive software stack — feature deployment, validation tooling, and the workforce that builds it — is expanding at double-digit rates simultaneously.
The Human Capital Behind the Shift
Software platforms don’t build themselves, and workforce data underscores how much this transition depends on engineering talent. The official unemployment rate of software developers (BDES, U. Department of Labour) for 2023-2033 will be approximately 17.9%, which is relatively high compared to other profession categories.
Currently, there are more than 1.5 million software developers working in the U.S., which encompasses all industries but not specific to automotive industry; they are based in the same talent pool that automakers now have to fight over as traditional tier-1 suppliers become creative and build their own software development plants.
Technical Challenges Driving Platform Investment
Several recurring engineering pressures explain why software platforms — not individual features — have become the investment priority:
- Validation complexity — With five ADAS features already above 90% penetration per NHTSA’s PARTS data, testing must scale without a matching increase in headcount, which is precisely what’s fueling the 12.4% CAGR in automated test tooling.
- Cross-supplier integration — With ADAS features now common across the large majority of new vehicles, ensuring software from different suppliers behaves predictably together has become a core platform requirement rather than a one-off integration task.
- Update cadence and safety compliance — Every remote software update carries regulatory and safety implications, requiring platforms that can validate, deploy, and document changes reliably.
- Talent availability — A software developer workforce growing at 17.9% still needs to be split across every industry competing for that talent, not automotive alone, making recruitment and retention a real constraint on platform development timelines.
How Software Platforms Are Changing Vehicle Development Cycles
Automotive software development is significantly influenced by digi-safe systems. The NHTSA’s PARTS initiative examined 168 cars manufactured between 2015-2023, accounting for a total of almost 98 million units. Results showed the growth of ADAS technology beyond luxury cars because, in 2023, 10 out of 14 ADAS features managed to achieve high levels of usage, with five of them occupying over 90% of the market.
In addition to the rapid acceptance of ADAS, the demand for automated validation and information management systems that make possible integration, testing, calibration, and deployment is also increasing. One more important aspect of providing access to these systems is the ability of getting over-the-air updates, which helps to improve cars at the post-production stage and guarantee compatibility of software in different vehicles’ generations.
The Role of Data and Connectivity in Software-Defined Vehicles
Data has become increasingly central to automotive software engineering as vehicles take on more connected functions. The PARTS dataset’s 2015–2023 timeframe shows how quickly these safety technologies have expanded. The dataset’s scale matters too, given its coverage of roughly 98 million vehicles, large enough to provide a substantial basis for examining adoption trends. For developers, this means platforms must operate reliably across varied configurations. The 14 ADAS features tracked span driver assistance, collision avoidance, and vehicle control. As various functions operate together in a single vehicle, software architecture becomes important in order to manage data among different sensors, different applications, and different interfaces. By the year 2023, five out of 14 of the tracked capabilities reached more than 90% penetrated cases. At that deployment level, the system is genuinely recognized as an engineering backbone, and application developers should be provided with standard interfaces so that the applications are able to share information without extra complexity.
Connectivity adds another layer: vehicles exchange information with external services while over-the-air capabilities support remote updates, linking the vehicle continuously to the development environment. The workforce facilitating automated processes is also increasing. According to U.S. Bureau of Labor Statistics, the employment of software developers is expected to grow 17.9% over the period from 2023 to 2033, which translates into various industries but also indicates high demand overall. Automotive software platforms enable ongoing development through integration of coding, testing, deployment, monitoring, and subsequent updating processes in an organized way. This workforce trend makes development efficiency more important. Standardized platforms let engineers share common frameworks and interfaces, helping teams manage complex programs while reducing duplication.
Cybersecurity and Continuous Software Updates in Modern Vehicles
Growing deployment of software-controlled functions raises the importance of secure software management. With 10 of 14 tracked ADAS features exceeding 50% penetration by 2023, cybersecurity now applies across a broad share of new vehicles. Over-the-air updates are central to continuous development. Rather than treating vehicle software as fixed at production, manufacturers use connected platforms to distribute validated changes, requiring systems that control versions and confirm compatibility. The comparison between the years 2021 and 2023 shows the importance of introducing new elements, which says that the penetration rate for features that have been adopted greatly increased from 0 to more than 75% during just two years, with a growing accent on reliability. To provide the required level of cybersecurity, it is necessary to implement it in the platform beforehand. Authentication, access control and controlled updates will protect vehicles’ software from unauthorized changes.
Before deploying software, testing is important, particularly when dealing with safety-related features of the product. Automated validation adds to continuous testing as new developments are introduced. It is in accordance with the growth of employment opportunities in the software development field, amounting to 17.9% according to BLS estimations for 2023-2033. PARTS statistics related to 168 types of vehicles, which collectively cover 98 million vehicles, indicate that in 2023, 10 features out of 14 of the Driver Assistance Systems (ADAS) have been getting more than 50% acceptance, while 5 features already received more than 90% of acceptance. All figures indicate that software development, testing, safety and continuous maintenance is becoming increasingly important.
How Automotive Software Platforms Support Continuous Development
Automotive software platforms enable ongoing development through integration of coding, testing, deployment, monitoring, and subsequent updating processes in an organized way. Developers can manage software versions, test changes, and identify compatibility issues before updates reach vehicles. This approach becomes increasingly important as multiple functions share computing resources and exchange data across connected systems. Standardized interfaces also allow engineering teams to reuse software components instead of developing separate solutions for every vehicle program. With 10 of 14 ADAS features exceeding 50% penetration by 2023, platform-based development provides a consistent foundation for managing widely deployed functions. It also supports faster iteration while maintaining traceability throughout the vehicle software lifecycle.
What This Means for the Automotive Industry
The direction is consistent across every dataset examined here: NHTSA-tracked ADAS feature penetration climbing from zero features above 75% to five features above 90% within two model years, a software test automation market compounding at 12.4% annually according to research, and a national developer workforce projected to grow nearly 18% over the next decade per BLS data. Vehicles are increasingly defined by the software platform underneath them, and by how quickly that platform can be built, tested, and updated safely. For automakers, suppliers, and technology partners, the competitive edge is shifting from who builds the best hardware to who builds the most reliable, continuously updatable software foundation beneath it.
Ashish Kolte is a Marketing Manager at Dataintelo with expertise in marketing, market intelligence, and business strategy. He combines marketing insights with industry research to help organizations understand market dynamics, identify growth opportunities, and make data-driven decisions. His areas of interest include emerging technologies, artificial intelligence, healthcare, industrial markets, and global business trends. Through his writing, Ashish shares research-backed perspectives on evolving industries and strategic market developments.
LinkedIn: https://www.linkedin.com/in/ashishkolte/